On Course to Achieve FY ’27 Outlook Following Solid Q2 Performance
NetScout (NTCT) reported fiscal Q2 ’27 results ahead of our estimates and consensus. The upside relative to our model was fully attributable to higher than anticipated service revenue, which combined with lower operating expenses, resulted in another solid beat on the bottom line. In contrast to last quarter, the Q2 performance was relatively normal in that no unusually large transactions were pulled into or slipped out of the quarter. Revenue from both the enterprise and service provider verticals exhibited modest growth, and from a product standpoint, mid-single digit growth in cybersecurity solutions more than offset a slight decline in service assurance solutions. Notable deals in the quarter included a high seven-figure service assurance win with a large financial institution and a low seven-figure order from a service provider leveraging NetScout’s cybersecurity products.
With 1H results tracking towards management’s prior FY ’27 expectations, guidance for the year was reaffirmed. For Q3, management’s outlook compared favorably with our previous top and bottom-line forecasts. We therefore made only minor adjustments to our prior modeling assumptions with the net effect being a modest increase in our estimates for this year and next. Our price target remains $50.00 based on an unchanged FY ’27 EV/EBITDA multiple of 12x.
Despite the positive results and outlook, shares of NTCT traded down considerably yesterday, albeit in a market that was also awash in red. In our view, there was no justification for the move. The only potential knocks were an expected drawdown of the product backlog in place at the start of the year and an inventory build that was high relative to historical norms but insignificant when considering the scale of NetScout’s business. As neither strikes us as a rational reason to dump the stock, we would be buyers here. In this regard, we note that NetScout was active in buying back shares during Q2 and given the downward move post-earnings, we surmise that will not change moving forward. Moreover, the company’s strong cash flow generation, significant liquidity on the balance sheet and lack of any leverage arguably warrants a far more aggressive approach to addressing the disconnect between NTCT’s share price and the underlying business fundamentals.
Exhibit I: Quarterly Results and Guidance Versus Expectations
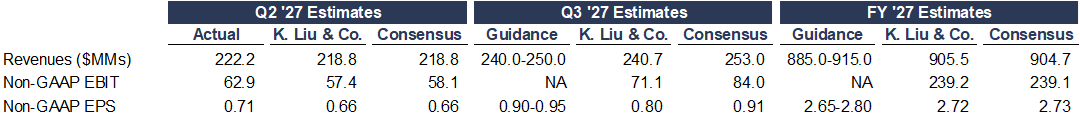
Sources: NetScout Systems; K. Liu & Company LLC; FactSet Estimates
Q2 revenue totaled $222.2 million (+1.4% Y/Y), exceeding our estimate and consensus of $218.8 million. Product sales of $89.9 million (-5.1% Y/Y) were in line with our projection, while service revenue of $132.3 million (+6.4% Y/Y) beat our estimate. Recall that several large government orders were pulled forward into the prior quarter, thereby limiting growth in Q2. By product, revenue from service assurance solutions comprised 64% of revenue and declined 1% Y/Y. Cybersecurity sales comprised the remaining 36% of sales and increased 7% from the prior year. By vertical, revenue from enterprise customers accounted for 61% of revenue and rose 1% Y/Y due to the pull-forward of government revenue into the prior quarter, while revenue from service providers comprised 39% of total revenue in Q2 and increased 2% Y/Y. NetScout exited Q2 with $20.9 million in product backlog, down from $32.9 million at the end of the prior quarter.
Non-GAAP gross margin of 80.9% was consistent with our 80.8% projection. Total operating expenses compared favorably with our estimates as both research and development and sales and marketing expenses came in below our forecasts. As a result, both non-GAAP operating income of $62.9 million (28.3% margin) and adjusted EBITDA of $66.5 million (29.9% margin) beat our estimates of $57.4 million and $60.6 million, respectively. Non-GAAP EPS of $0.71 also exceeded our estimate and consensus of $0.66.
Cash and investments at quarter-end totaled $571.3 million, and the company remained debt free. In Q2, NetScout used $15.1 million in cash flow from operations, primarily to build inventory to avoid potential supply chain risk, while capital expenditures consumed another $2.7 million. The company also repurchased 2.0 million shares for $77.0 million.
Management’s Q3 outlook calls for revenue of $240.0-$250.0 million and non-GAAP EPS of $0.90-$0.95, both of which compared favorably with our previous estimates of $240.7 million and $0.80, respectively. Although consensus was a shade above the high-end of management’s Q3 revenue guidance, we believe that is largely a function of timing as full year expectations remain unchanged on the top and bottom lines. For FY ‘27, management reiterated guidance for revenue of $885.0-$915.0 million and non-GAAP EPS of $2.65-$2.80.
Exhibit II: Estimate Revisions
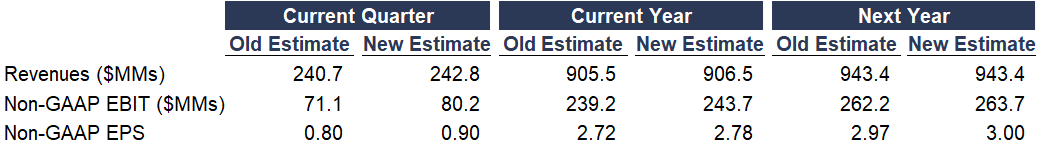
Source: K. Liu & Company LLC
With the results and outlook tracking according to our expectations, we made only minor adjustments to our quarterly revenue mix assumptions and operating expense forecasts. The net effect was a nominal increase in our estimates for FY ’26 and FY ‘27. We continue to expect annual top and bottom line growth in the mid-single digit and high-single digit range, respectively, across our forecast horizon.
Our report with model and disclosures is available here.
Disclosure(s):
K. Liu & Company LLC (“the firm”) receives or intends to seek compensation from the companies covered in its research reports. The firm has not received any compensation from NetScout Systems (NTCT) in the past 12 months.
The analyst, a member of the analyst’s household, and/or an account in which the analyst exercises discretion hold(s) a long position in the common stock of NetScout Systems (NTCT).