Record New Business Bookings at ClearanceJobs Fuel Q3 Outperformance
DHI Group (DHX) posted strong Q3 results highlighted by a return to organic double-digit bookings growth for ClearanceJobs, moderating declines at Dice and robust free cash flow generation that allowed for both significant share repurchases and a reduction in debt. Revenue from both ClearanceJobs and Dice beat our expectations, resulting in both adjusted EBITDA and non-GAAP EPS exceeding our estimates. Per management, ClearanceJobs delivered the highest level of quarterly new business bookings in its history as its addressable market opportunity continues to expand alongside a growing number of well-funded DefenseTech companies. At Dice, bookings were in line with our forecast as a slightly higher revenue retention rate offset an uptick in churn among smaller customers. Worth noting, a portion of that churn reflects a concerted effort to shift smaller customers paying less than $6,500 annually to the self-service channel. As plans in that channel are paid on a monthly basis, those subscribers are not included in DHI Group’s reported subscriber metrics, which are based on customers with annual and multi-year agreements. Although still early, the self-service channel is already generating monthly revenue of approximately $100,000 and should scale without any material investments in sales headcount.
Reflecting the upside in Q3, management raised its adjusted EBITDA margin target for the year from 25% to 26% and narrowed its prior revenue guidance. The revised guidance implies Q4 results largely consistent with our previous expectations. More importantly, the results and outlook suggest management remains on track to deliver renewed double-digit growth at ClearanceJobs in FY ’27 along with slow and steady improvement at Dice. We therefore maintain our prior Q4 ’26 and FY ’27 projections. We also introduce our FY ’28 estimates, which reflect an acceleration in top line growth and margin expansion. Our price target increases from $5.00 to $5.50 based on the same EV/Sales multiple of 2x we used previously but now rolled forward to our FY ’27 projections.
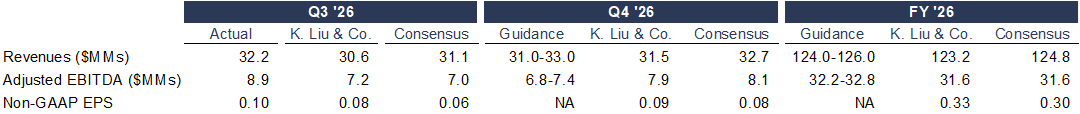
Exhibit I: Reported Results and Guidance Versus Expectations
Sources: DHI Group; K. Liu & Company LLC; FactSet Estimates
Q3 revenue of $32.2 million (+0.4% Y/Y) exceeded our $30.6 million estimate and the Street’s $31.1 million. Both ClearanceJobs revenue of $16.5 million (+18.4% Y/Y) and Dice revenue of $15.7 million (-13.5% Y/Y) outpaced our projections of $15.6 million and $15.1 million, respectively. Revenue from the acquisition of Point Solutions Group of $2.0 million, which is included in the ClearanceJobs segment, was consistent with our forecast.
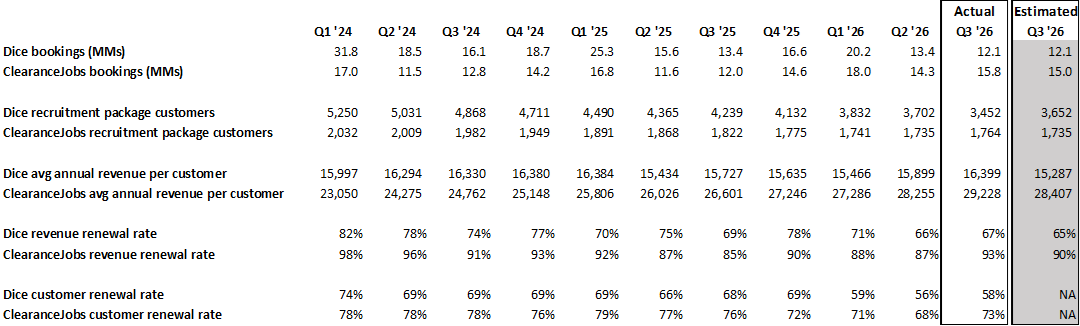
ClearanceJobs bookings of $15.8 million (+31.7% Y/Y) were ahead of our $15.0 million estimate, while Dice bookings of $12.1 million (-9.5% Y/Y) were in line with our projection. The upside in ClearanceJobs bookings was attributable to a record quarter for new business bookings as well as a slightly higher revenue retention rate than we modeled. Consistent with the past several quarters, average revenue per customer continued to move higher for both ClearanceJobs and Dice. We were pleased to see the number of ClearanceJobs customers return to growth on a sequential basis. Although customer counts continued to decline at Dice, management noted that a portion of the attrition arose from a concerted effort to move customers paying less than $6,500 annually to the self-service channel, which is now generating monthly revenue of approximately $100,000.
Exhibit II: Key Metrics
Sources: DHI Group; K. Liu & Company LLC
Gross margin of 79.2% was slightly below our 79.6% assumption due to higher costs at both ClearanceJobs and Dice. However, this was more than offset by total operating expenses (adjusted for $1.4 million in severance, professional fees and related costs that were not included in our model) coming in below our estimate. As a result, adjusted EBITDA of $8.9 million (27.6% margin) topped our $7.2 million estimate and the Street’s $7.0 million. Non-GAAP EPS of $0.10 also beat our estimate of $0.08 and the Street’s $0.06.
In Q3, DHI Group generated $7.2 million in cash flow from operations and used $1.9 million for capital expenditures. Cash at quarter-end totaled $3.2 million, while outstanding debt declined from $32.0 million to $30.0 million. During the quarter, the company repurchased 830,350 shares at a total cost of $3.7 million, leaving $0.8 million remaining under the current repurchase authorization.
As for guidance, management narrowed its prior FY ‘26 revenue expectations from $124.0-$128.0 million to $124.0-$126.0 million and raised its adjusted EBITDA margin target from 25% to 26%. The revised outlook implies Q4 revenue and adjusted EBITDA of $31.0-$33.0 million and $6.8-$7.4 million, respectively. Prior to revisions, we were projecting Q4 revenue and adjusted EBITDA of $31.5 million and $7.9 million, while consensus stood at $32.7 million and $8.1 million.
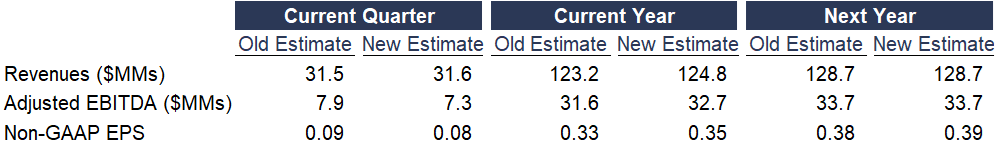
Exhibit III: Estimate Revisions
Source: K. Liu & Company LLC
Our FY ’26 estimates move higher due to the upside in Q3 and no material changes to our prior expectations for Q4. Our FY ’27 estimates remain essentially unchanged as we continue to model strong double-digit growth for the ClearanceJobs segment and moderating declines at Dice. We also introduce our FY ’28 projections, which reflect revenue of $137.1 million (+6.5% Y/Y) and adjusted EBITDA of $36.6 million (26.7% margin).
Our report with model and disclosures is available here.
Disclosure(s):
K. Liu & Company LLC (“the firm”) receives or intends to seek compensation from the companies covered in its research reports. The firm has received compensation from DHI Group, Inc. (DHX) in the past 12 months for “Sponsored Research.”
Sponsored Research produced by the firm is paid for by the subject company in the form of an initial retainer and a recurring monthly fee. The analysis and recommendations in our Sponsored Research reports are derived from the same process and methodologies utilized in all of our research reports whether sponsored or not. The subject company does not review any aspect of our Sponsored Research reports prior to publication.