Mixed Q2 Results Prompt Reset in Expectations
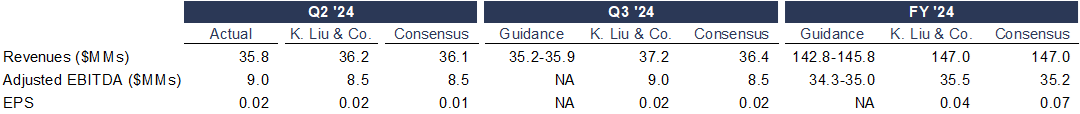
DHI Group (DHX) reported mixed Q2 ’24 results as adjusted EBITDA beat consensus and our estimate despite a slight revenue shortfall. As anticipated, bookings underperformed amid ongoing sluggishness in the economy. However, we were surprised to see an uptick in churn as the primary cause of lower bookings, which management attributed in part to the loss of two large customers. One of the customers was an automobile manufacturer instituting budget cuts and the other a staffing and recruiting firm that divested its IT staffing division; both represent potential win-backs in the future, in our opinion. Gross margin was below our assumption due to the combined impact of lower revenue and higher costs, but this was more than offset by lower operating expenses. As a result, EPS were in line with our estimate and a penny ahead of consensus.
Looking forward, management expects the soft demand environment to persist in the near-term. As such, guidance for Q3 calls for a mid-single digit decline in revenue and bookings, falling short of our prior estimates and consensus. Moreover, revenue for the full year is also expected to fall at a mid-single digit rate versus the low single digit decline originally anticipated, and an inflection point in bookings growth has been pushed out to next year. On a more positive note, management continues to guide for an adjusted EBITDA margin of 24% in FY ’24, reflecting expected cost savings from the company’s restructuring last month partially offset by incremental investments in AI-related campaigns.
Worth noting, positions seeking AI skills comprised 27% of new job postings in June, up from 15% at the start of the year according to Lightcast. Per management, job postings on Dice increased 30% between Q1 and Q2 and exhibited a similar trend in terms of demand for AI skills. Considering that average monthly applications submitted through Dice rose 85% from Q1, we are optimistic that AI-driven demand for technologists and the end of the “Big Stay” could eventually align to create the tight labor market conditions that were a boon for DHI Group’s online career marketplaces in the aftermath of the COVID pandemic, perhaps as soon as next year.
While we continue to expect improved bookings growth in FY ’25, we lower our revenue, bookings and adjusted EBITDA estimates for this year and next to reflect the performance to date and the pushout of renewed bookings growth to Q1 ‘25. Our price target also declines from $7.00 to $5.25 based on a FY ’25 EV/Sales multiple of 2.0x. We note that our prior target was derived from a FY ’24 EV/Sales multiple of 2.5x, but with no revenue growth anticipated until FY ’26, we think multiple expansion will be constrained in the interim. That said, we still believe shares are significantly undervalued, and we remain bullish on DHI Group’s long-term growth prospects.
Exhibit I: Reported Results and Guidance Versus Expectations
Sources: DHI Group; K. Liu & Company LLC; FactSet Estimates
Q2 revenue of $35.8 million (-7.0% Y/Y) was slightly below our estimate of $36.2 million and consensus of $36.1 million. Relative to our model, the revenue shortfall was wholly attributable to Dice, which generated revenue of $22.6 million (-14.1% Y/Y) versus our $22.9 million estimate. Revenue from ClearanceJobs totaled $13.3 million (+8.2% Y/Y) and was in line with our projection.
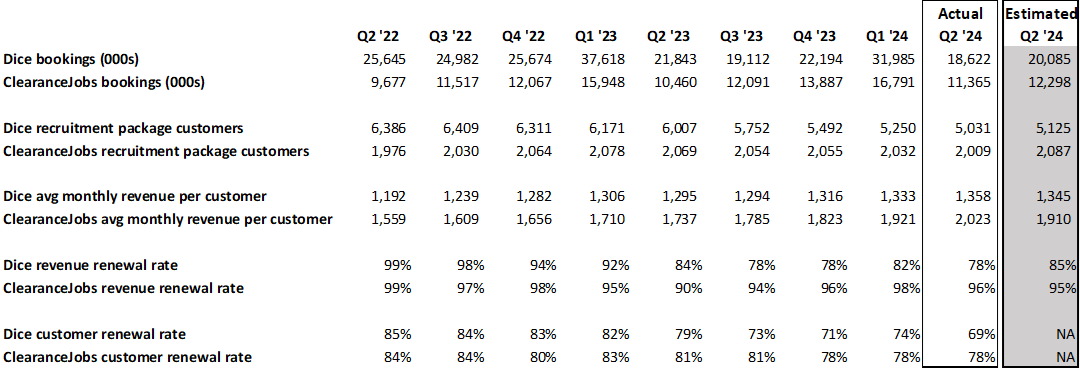
Dice bookings of $18.6 million (-14.7% Y/Y) were below our $20.1 million projection. Although we expected bookings to decline due to challenging market conditions, we were somewhat surprised by the sequential increase in churn as retention rates had seemingly stabilized and improved in the prior quarter. Per management, much of the churn continues to occur among those customers spending less than $10,000 on an annualized basis but there were two more significant customer losses in Q2. As the circumstances surrounding these losses appear to be idiosyncratic, we expect renewal rates to bounce back over the coming quarters.
ClearanceJobs bookings of $11.4 million (+8.7% Y/Y) exhibited accelerating growth on a sequential basis but fell short of our loftier $12.3 million target. We had assumed a more significant benefit from the closing of deals delayed in Q1, but government contractors appear to be taking a measured approach to spending amid ongoing political uncertainty. That said, ClearanceJobs’ retention and average annual revenue metrics remain healthy and continue to compare favorably with our assumptions.
Exhibit II: Key Metrics
Sources: DHI Group; K. Liu & Company LLC
Gross margin of 85.5% was below our assumption of 86.3% due to lower revenue and higher costs than modeled. However, total operating expenses were also below our estimate, primarily reflecting lower sales and marketing and general and administrative expenses than we projected. As a result, adjusted EBITDA of $9.0 million (25.0% margin) beat our estimate and consensus of $8.5 million. EPS of $0.02 were in line with our estimate and a penny ahead of consensus.
In Q2, DHI Group generated $9.1 million in cash flow from operations and used $3.5 million for capital expenditures. Cash at quarter-end totaled $3.0 million, while outstanding debt declined from $41.0 million to $35.0 million. Of note, DHI Group’s net leverage ratio now sits at approximately 1x, resulting in a 25bps reduction in the company’s interest rate moving forward. With net leverage now at management’s targeted range entering the year, we believe excess cash flow could and likely should be reallocated to share repurchases, although further reductions in debt also remain a possibility.
Reflecting bookings to date and expectations for the demand environment to remain relatively sluggish through year-end, management lowered its expectations for revenue growth in FY ’24 from a low single digit decline to a mid-single digit decline, while maintaining its prior adjusted EBITDA margin target of 24%. For Q3, revenue is expected to decline 4%-6% Y/Y, implying revenue of $35.2-$35.9 million. Prior to revisions, we were projecting Q3 revenue of $37.2 million, while consensus was at $36.4 million.
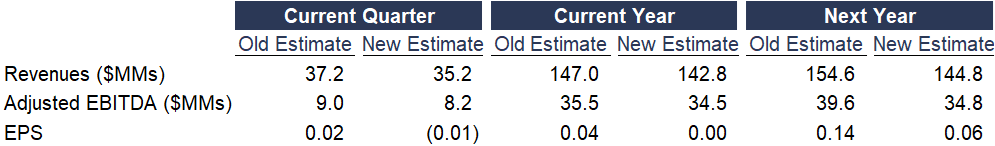
Exhibit III: Estimate Revisions
Source: K. Liu & Company
We lower our revenue estimates for this year and next as we now expect bookings growth to return to positive levels in Q1 ’25 as opposed to Q3 ‘24. Although our operating expense assumptions also decline across our forecast horizon, the net effect is a decrease in our adjusted EBITDA and EPS estimates.
Our report with model and disclosures is available here.
Disclosure(s):
K. Liu & Company LLC (“the firm”) receives or intends to seek compensation from the companies covered in its research reports. The firm has received compensation from DHI Group, Inc. (DHX) in the past 12 months for “Sponsored Research.”
Sponsored Research produced by the firm is paid for by the subject company in the form of an initial retainer and a recurring monthly fee. The analysis and recommendations in our Sponsored Research reports are derived from the same process and methodologies utilized in all of our research reports whether sponsored or not. The subject company does not review any aspect of our Sponsored Research reports prior to publication.