Delivers Strong Q4 Results and Positive Outlook for FY '24
NetScout Systems (NTCT) reported fiscal Q4 ’23 results above our estimates and consensus. Both product and service revenue outpaced our expectations as another quarter of strong growth in the service provider vertical more than offset ongoing macro-related softness in the enterprise vertical. Worth noting, NetScout’s backlog of fulfillable orders increased by approximately $10 million on a sequential basis, resulting in total backlog remaining relatively flat despite the completion of some previously awarded RF Propagation Modeling (RFPM) projects. We had expected backlog to begin normalizing towards the lower levels seen historically, so we were pleasantly surprised by the strong bookings performance and enhanced near-term visibility. Along with the revenue upside, product gross margin was also higher than we assumed, which in turn helped to offset higher operating expenses than we modeled. As a result, both adjusted EBITDA and non-GAAP EPS exceeded our expectations with the latter further benefiting from a lower tax rate.
Although the strength in Q4 was certainly positive, we were even more impressed by management’s initial guidance for FY ’24. Considering macro uncertainty continues to abound and a challenging comparison presented by the significant ramp in RFPM projects last year, we were expecting a downtick in revenue and non-GAAP EPS for FY ’24. In contrast, management’s outlook for the year calls for low single-digit revenue growth along with continued earnings expansion, both of which compared favorably with Street expectations heading into the print. Underpinning the strong guidance for FY ’24 are expectations for ongoing service provider investments in 5G, improved sales execution for the expanded Omnis security portfolio and the introduction of two new DDoS products, Dynamic DDoS and Mobile DDoS Security.
We raise our estimates for this year and next, primarily reflecting higher growth expectations partially offset by an uptick in operating expenses. Our price target also increases from $38.00 to $42.00 based on an unchanged FY ‘24 EV/EBITDA multiple of approximately 12x. Notwithstanding yesterday’s post-earnings pop, shares of NTCT are still trading well below recent highs despite the company’s consistent execution and enhanced financial position. We believe this creates an attractive buying opportunity and note that management also plans to be active in repurchasing shares.
Exhibit I: Quarterly Results and Guidance Versus Expectations
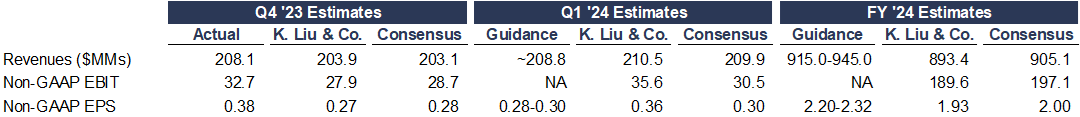
Sources: FactSet Estimates; K. Liu & Company LLC; NetScout Earnings Release
Q4 revenue of $208.1 million (+8.8% Y/Y) exceeded our estimate of $203.9 million and consensus of $203.1 million. Product sales of $91.3 million (+11.1% Y/Y) were ahead of our $90.0 million estimate, and service revenue of $116.8 million (+7.1% Y/Y) also surpassed our $113.9 million projection. Revenue from service assurance products comprised 72% of revenue and grew 12% Y/Y, while cybersecurity sales made up the remaining 28% of sales and increased 2% Y/Y. The strong growth in service assurance sales coincided with robust growth in the service provider vertical, which accounted for 51% of revenue in the quarter and grew 32% Y/Y. Contribution from the enterprise vertical comprised the remaining 49% of revenue and declined 8% Y/Y due to lingering concerns around the macro environment. Backlog at quarter-end was down slightly from $54 million to $50 million, reflecting an increase in fulfillable orders from $31 million to $41 million offset by a decline in RFPM projects from $23 million to $9 million as previously awarded projects were completed.
Non-GAAP gross margin of 77.6% was well above our 74.2% assumption as product gross margin of 84.3% easily exceeded our 75.0% estimate. The upside reflected both higher sales volumes and above average margins on RFPM revenue recognized in the quarter. Total operating expenses ran higher than our projections, principally on the R&D and G&A lines. Regardless, both non-GAAP operating income of $32.7 million (15.7% margin) and adjusted EBITDA of $38.0 million (18.3% margin) beat our estimates of $27.9 million and $33.1 million, respectively. Non-GAAP EPS of $0.38 also beat our $0.27 estimate and the Street’s $0.28.
Cash and investments at quarter-end totaled $427.9 million, while outstanding debt stood at $100.0 million. In Q4, NetScout generated free cash flow of $110.6 million and repaid $100.0 million in debt. Turning to the outlook, management’s initial guidance for FY ’24 calls for revenue of $915.0-$945.0 million and non-GAAP EPS of $2.20-$2.32. Both the top and bottom line guidance ranges exceeded our estimates and consensus. For Q1, management expects revenue to be comparable to last year’s performance while non-GAAP EPS increases by $0.04-$0.06, implying revenue of approximately $208.8 million and non-GAAP EPS of $0.28-$0.30. Prior to revisions, we were projecting Q1 revenue of $210.5 million and non-GAAP EPS of $0.36, while consensus called for $209.9 million and $0.30, respectively.
Exhibit II: Estimate Revisions
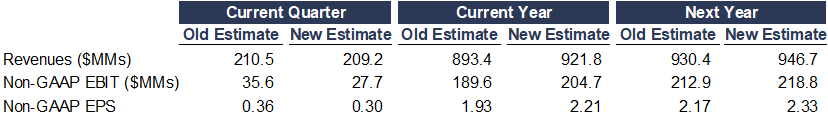
K. Liu & Company LLC
We raised our estimates for this year and next, primarily reflecting higher growth expectations for both product and service revenues. We also increased our gross margin assumptions, although this was partially offset by higher operating expenses. All told, our revised estimates skew towards the lower end of management’s current outlook, leaving room for upside should the company’s newer product offerings gain traction.
Our report with model and disclosures is available here.
Disclosure(s):
The analyst, a member of the analyst’s household, and/or an account in which the analyst exercises discretion hold(s) a long position in the common stock of NetScout Systems (NTCT).