Q1 '22 Earnings Preview
CTG, Inc. (CTG) reports Q1 ’22 results on Tuesday, May 10. We believe the company is off to a solid start for the year and therefore expect results consistent with our estimates and consensus. Amid the recovery from the pandemic, CTG has grown its pipeline and seen conversion rates gradually improve, culminating in a strong finish to FY ’21. We believe the demand environment remained healthy in Q1, particularly for consulting services in areas such as cloud migration and application development, which should partially offset anticipated declines in the Non-Strategic Technology Services segment. Although the crisis in Ukraine and FX fluctuations introduce potential headwinds to growth in the Europe IT Solutions and Services segment, we note that CTG has no direct exposure to the regions affected by the war and thus far, Q1 results from those exposed to Europe point to a solid economic backdrop. That said, we assume the added uncertainty from recent geopolitical events will leave management content to simply reaffirm its prior FY ’22 guidance for revenue of $375.0-$395.0 million and non-GAAP EPS of $0.64-$0.72 at this juncture. Our price target remains $13.00 based on a FY ’22 EV/EBITDA multiple of 8x.
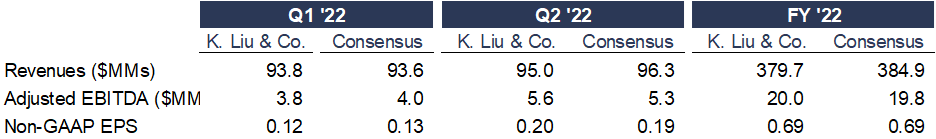
Exhibit I: Our Estimates Versus Consensus
Source: K. Liu & Company LLC; IBES Estimates
We project Q1 revenue of $93.8 million (-3.5% Y/Y), modestly above consensus of $93.6 million. Recall that management’s outlook for the year assumes that revenue will be at its lowest point in Q1 and reflect a slight Y/Y decline. Worth noting, Q1 has one less billing day than the year ago period and will also be impacted by CTG’s strategic shift away from lower margin staffing services, which is expected to reduce full year revenue by $25.0-$30.0 million. Regardless, the increasing mix of IT Solutions and Services revenue should benefit gross margin, which we expect to expand 70 basis points from a year ago to 22.2%. Our model also reflects operating expenses relatively consistent with last year and down on a sequential basis, resulting in adjusted EBITDA of $3.8 million versus consensus of $4.0 million. Our non-GAAP EPS estimate of $0.12 sits a penny below consensus. Aside from the usual questions on sales cycles, pipeline growth and conversion rates, we expect Europe to be a focal point on the call given that the region has been a cornerstone of CTG’s strategic shift towards IT Solutions but now faces greater uncertainty. In any event, we remain comfortable with our estimates for Q2 and FY ’22.
Our report with model and disclosures is available here.
Disclosure(s):
K. Liu & Company LLC (“the firm”) receives or intends to seek compensation from the companies covered in its research reports. The firm has received compensation from CTG, Inc. (CTG) in the past 12 months for “Sponsored Research.”
Sponsored Research produced by the firm is paid for by the subject company in the form of an initial retainer and a recurring monthly fee. The analysis and recommendations in our Sponsored Research reports are derived from the same process and methodologies utilized in all of our research reports whether sponsored or not. The subject company does not review any aspect of our Sponsored Research reports prior to publication.