Q4 '21 Earnings Preview
DHI Group, Inc. (DHX) reports Q4 ’21 results on Tuesday, February 8. Given tight labor market conditions and persistently high quit rates throughout 2H ‘21, we believe DHI Group exited the year on a high note. According to data from the U.S. Bureau of Labor Statistics, the number of job openings in December was nearly 62% higher than a year ago and increased nearly 61% Y/Y on average for the three-month period ending December 31, 2021. Although moderating slightly from the prior month, the number of quits also remained near record highs, increasing 27% Y/Y in December and over 29% Y/Y on average for the three-month period. Also worth noting, Staffing Industry Analysts’ Pulse survey indicated median revenue growth among IT staffing firms, a key customer segment for Dice, was up 25% Y/Y in December. Amid this favorable backdrop, we expect DHI Group to post strong results consistent with management’s outlook for revenue growth approaching 20% and an adjusted EBITDA margin also at or near 20%. Of course, the company’s large base of recurring revenues and previously disclosed bookings metrics lend further confidence to our view.
Exhibit I: U.S. Job Openings in Thousands
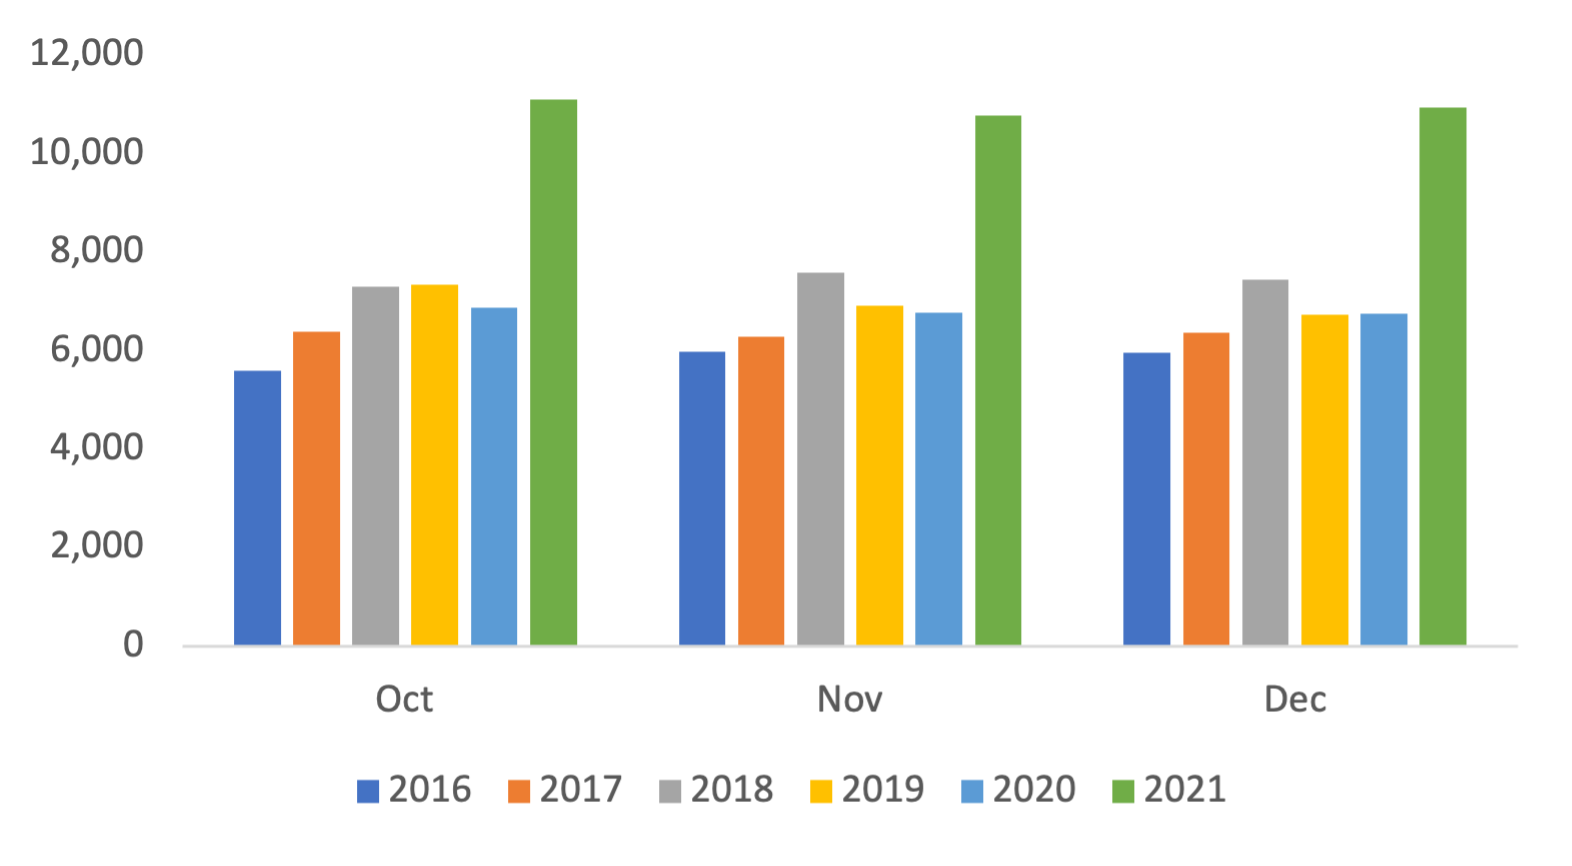
Source: U.S. Bureau of Labor Statistics Job Openings and Labor Turnover Survey
Exhibit II: U.S. Quits in Thousands
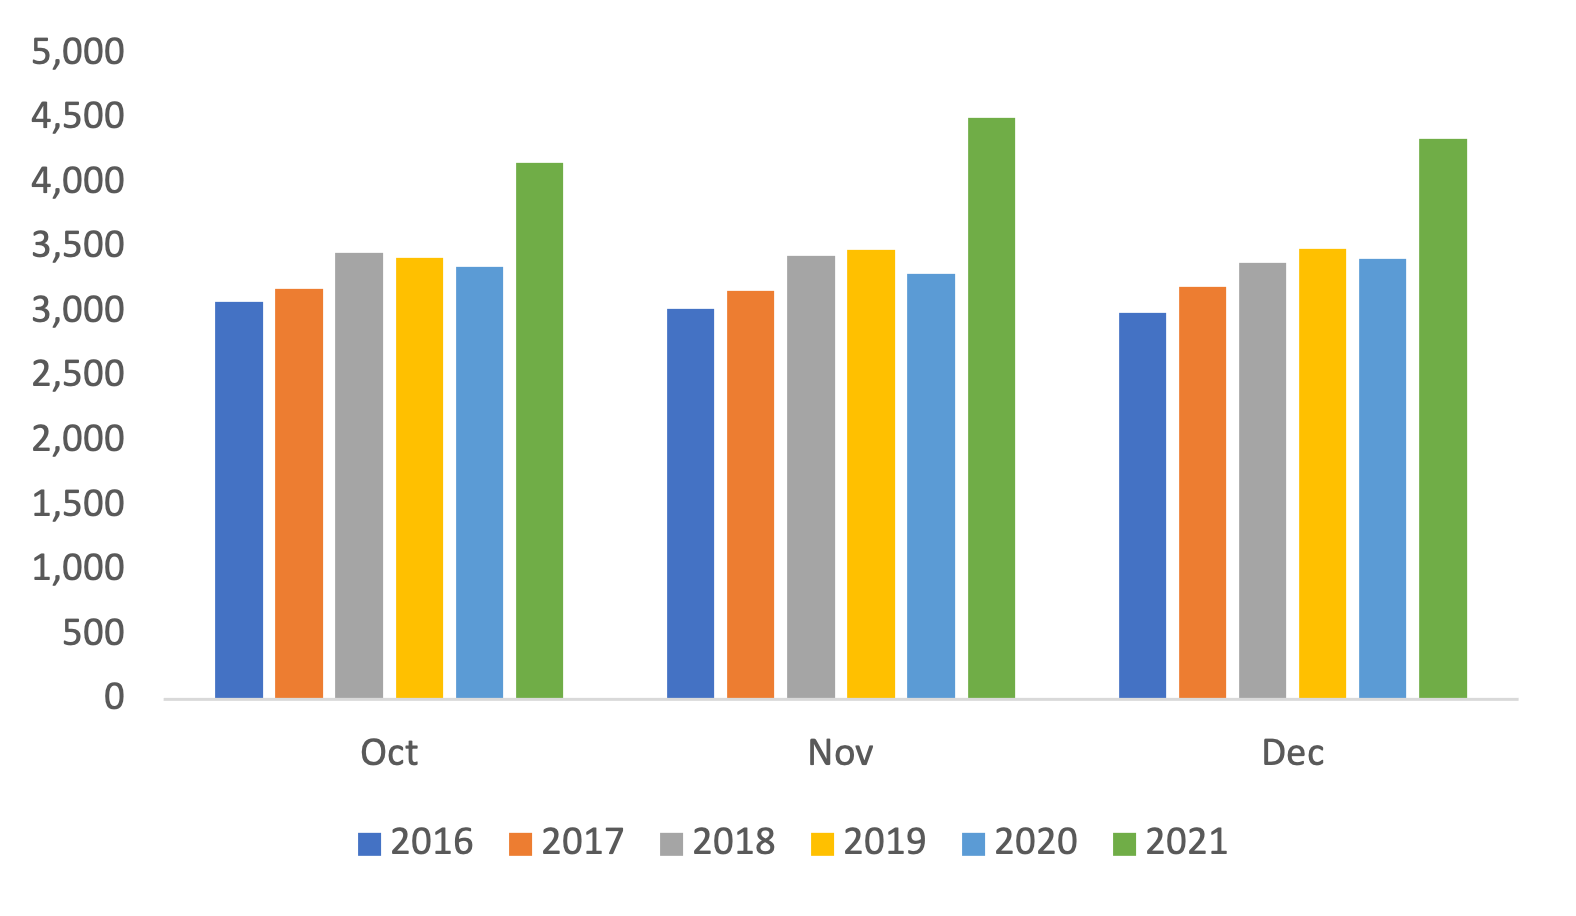
Source: U.S. Bureau of Labor Statistics Job Openings and Labor Turnover Survey
Our Q4 estimates are generally in line with consensus. We project revenues of $31.9 million (+18% Y/Y), comprised of $23.1 million (+19% Y/Y) from Dice and $8.8 million (+15% Y/Y) from ClearanceJobs. From a bookings standpoint, we expect continued strong growth across both platforms and have modeled Dice and ClearanceJobs bookings of $25.4 million (+32% Y/Y) and $9.0 million (+18% Y/Y), respectively. Our adjusted EBITDA estimate of $6.6 million (20.8% margin) reflects over 100bps of gross margin expansion versus the prior year period and improved leverage of operating expenses despite a significant ramp in sales and marketing investments. Our EPS estimate of breakeven is consistent with consensus.
Exhibit III: Our Estimates Versus Consensus
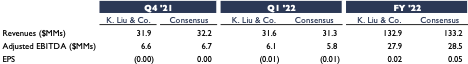
Sources: K. Liu & Company LLC; IBES Estimates
Looking forward, recall that management’s guidance over the past year has been more qualitative in nature, calling for a return to positive revenue growth and establishing a floor of sorts with respect to adjusted EBITDA margin. While it remains to be seen if management plans to provide more specific financial targets, we expect any commentary to be supportive of our estimates and consensus, both of which reflect low double-digit growth and an adjusted EBITDA margin in the low 20% range. Aside from the aforementioned labor market conditions, which we expect to remain a tailwind for the foreseeable future, we note that the competitive landscape is also becoming more favorable given Stack Overflow’s plans to discontinue its Jobs and Developer Story features by the end of Q1 ’22. Considering our expectations for another strong quarter and the recent downdraft in shares amid broader market weakness, we continue to view shares of DHX as a compelling investment opportunity. Our price target remains $8.00, representing a FY ’22 EV/Sales multiple of 3x.
Our report with model and disclosures is available here.
Disclosure(s):
K. Liu & Company LLC (“the firm”) receives or intends to seek compensation from the companies covered in its research reports. The firm has received compensation from DHI Group, Inc. (DHX) in the past 12 months for “Sponsored Research.”
Sponsored Research produced by the firm is paid for by the subject company in the form of an initial retainer and a recurring monthly fee. The analysis and recommendations in our Sponsored Research reports are derived from the same process and methodologies utilized in all of our research reports whether sponsored or not. The subject company does not review any aspect of our Sponsored Research reports prior to publication.