Stamps.com Q1 '20 Earnings Preview
Stamps.com (STMP) reports Q1 ’20 results on Thursday, May 7, after the close. We expect results to compare favorably with our model, and while our estimates are mixed versus current consensus forecasts, we think upside relative to Street expectations is the likely outcome. Underpinning our view is the usual read-through from the United States Postal Service’s (USPS) monthly PC Postage data and favorable commentary from other companies levered to e-commerce regarding business trends both pre- and post-pandemic related shutdowns in March. While positive e-commerce trends appear to have continued through April, the impact of COVID-19 on the economy heading into 2H ’20 remains exceedingly murky. As such, we believe Stamps.com simply maintaining its current FY ’20 guidance would represent a best-case scenario, but we would hardly be surprised if the company were to pull its outlook for the year. Separately, we note that the USPS filed a request to remove customized postage from the mail classification schedule on May 1, and no vendors will be authorized as part of the customized postage program as of June 16, 2020. We have therefore halved our estimate for Customized Postage revenue in Q2 and removed any associated revenue and expenses from our model beyond that time. The loss of these non-core revenues has only a nominal impact on our estimates, and we are therefore maintaining our price target of $160.00 based on a FY ’20 EV/EBITDA multiple of 20x.
Shares of Stamps.com are now trading right around our price target, raising the question of what to do with the stock here. Considering our expectations for the upcoming print, we see no reason to bail on the stock and contend that Stamps.com should remain a core holding given its dominant market position and favorable long-term growth prospects. That said, we expect shares to be somewhat rangebound in the near-term as the uncertain outlook for the global economy in 2H ’20 is likely to keep any enthusiasm around recent e-commerce trends in check. Aside from the rapid climb in unemployment, other external factors such as political wrangling over the USPS’ access to a $10 billion loan approved by Congress as part of the The Cares Act also create the specter of another USPS-related overhang on shares. Although we believe the prospect of a USPS shutdown in the coming months is miniscule, we are unwilling to dismiss the risk outright as the current Administration has yet to pass a USPS reform bill that had bipartisan support and buy-in from key stakeholders, has not taken any action to put the USPS on a sustainable financial path despite establishing a task force to recommend the way forward, and believes raising prices on package delivery is the path to salvation amidst rising competition and a global pandemic. With all this in mind, some profit-taking and rebalancing of the portfolio may be in order for those, like us, that have benefited from the strong absolute and relative performance to date.
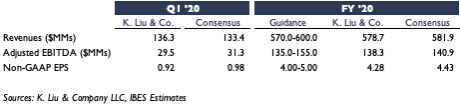
Our Q1 estimates include revenue of $136.3 million, adjusted EBITDA of $29.5 million and non-GAAP EPS of $0.92, which are mixed relative to Street expectations for revenue of $133.4 million, adjusted EBITDA of $31.3 million and non-GAAP EPS of $0.92. As it relates to revenue, we expect domestic strength to more than offset any softness from the company’s international exposure, which primarily arises from the Global Advantage Program and MetaPack. The variance in our profitability expectations relative to consensus likely stems from our projections for incremental sales and marketing expenses. In this regard, we believe pressure on advertising spend as the pandemic took hold may have allowed the company to capitalize on more attractive rates and acquire more subscribers to boot as merchants lacking an online presence had to pivot quickly. Given these factors, we expect Stamps.com’s Q1 results to meet or exceed Street expectations.
As for data points supporting our view, monthly USPS PC Postage revenue data reflected a deceleration in growth to 6% in the first two months of the quarter. While we always prefer to see more growth, the magnitude of the deceleration was consistent with our assumptions for Stamps.com’s postage printed metric, an indicator of potentially monetizable transactions. More significantly, the shutdown of nonessential businesses and shelter-in-place orders instituted in March provided a tailwind to B2C e-commerce, at least according to UPS, which saw B2C volume growth spike to the high-teens and approach 70% of its domestic volume by quarter-end. Of course, Stamps.com’s new strategic partnership with UPS is timely in this regard. Competitor Pitney Bowes also experienced healthy growth of 11% in its domestic parcels business during Q1 and noted domestic parcel deliveries grew in excess of 40% in April. eBay expressed similar sentiments, indicating its key metrics were outperforming prior to the COVID-19 outbreak in Q1 and certain marketplace categories associated with home confinement surged in late March. Demand has since expanded across all verticals and driven GMV growth in excess of 20% since the start of April. Amazon also experienced a major surge in customer demand beginning in early March, although the company indicated demand for discretionary items fell during that time. Thus far, the company has seen strong demand in Q2 as well. We believe these positive domestic trends bode well for Stamps.com’s recent and near-term performance and should mitigate any international challenges associated with the Global Advantage Program and MetaPack. In regard to the former, cross-border commerce has certainly been affected by the COVID-19 pandemic. As of May 1, the USPS had suspended outbound mail services to 112 international destinations, and in its earnings call yesterday, Pitney Bowes (PBI) indicated that its cross-border business experienced a decline in demand due to restrictions on international shipments. As for MetaPack, economic conditions in Europe deteriorated in Q1, but we note that our estimates for the segment already reflected a Y/Y decline.
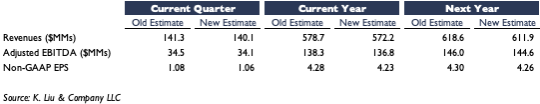
While we plan to await the upcoming earnings call before hazarding any guess for how the latter half of the year may unfold, the USPS’ recent filing (Docket No. MC2020-126) to request the removal of customized postage from the mail classification schedule signals the end of customized postage. Stamps.com has long considered this portion of its business to be non-core, and in recognition of the lack of demand and interested vendors, the USPS has determined that the business risks of continuing the program outweigh any potential benefits. The filing indicates that the USPS has revoked the authorization of its last remaining vendor, which we presume to be Stamps.com, meaning there will be no authorized vendors as of June 16, 2020. With this in mind and taking into account the likelihood of depressed demand given the current environment, we have halved our Q2 customized postage revenue estimate and removed all associated revenue and costs in 2H ’20 and beyond. The impact on our estimates for this year and next was fairly negligible, and we surmise could be more than made up for through outperformance thus far in the year or a continuation of strong e-commerce trends beyond Q2.
Our report with model and disclosures is available here.
Dislcosure(s):
The analyst, a member of the analyst’s household, and/or an account in which the analyst exercises discretion hold(s) a long position in the common stock of Stamps.com (STMP).