Q1 ’19 Earnings Preview for Stamps.com
Stamps.com (STMP) reports Q1 ’19 results after the market closes on Wednesday, May 8. Our usual course is to reference the United States Postal Service’s (USPS) monthly data disclosed thus far for the quarter and extrapolate a reasonable scenario for where the company’s results are likely to fall. In this regard, monthly USPS data available through February points to strong double-digit growth in PC Postage revenues, which considering our assumption for a mid-single digit increase in customer postage printed bodes well for outperformance relative to our projections. As our quarterly estimates sit above consensus, this would also coincide with a call for a beat in Q1. While we are willing to go out on a limb and make that call, we concede that the company’s termination of a key incentive agreement with the USPS creates a considerable level of uncertainty in the accuracy of our analysis.
Other factors to consider ahead of the print include the actions taken by Stamps.com to recoup its costs for servicing high-volume shippers with USPS negotiated service agreements and foreign currency fluctuations, which have more relevance today given the acquisition of MetaPack. Regarding the former, Pitney Bowes’ (PBI) commentary in its Q1 ’19 earnings call suggested little has changed in the USPS ecosystem since Stamps.com ended its exclusive agreement with the USPS. Thus, the risk that customer churn or lost incentive fees have been higher than reflected in Street expectations appears minimal as it relates to Q1. As for FX, the strengthening of the U.S. dollar relative to Q1 ’18 has presented growth headwinds for many reporting companies this earnings season, but as MetaPack was not in the year-ago period and the Euro and Pound have rebounded slightly since Stamps.com last reported, we do not anticipate a drag from FX on the company’s Q1 results and outlook for the year.
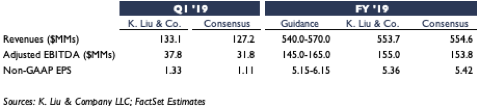
Speaking of guidance, the combination of strategic changes in its carrier relationships coupled with the seasonal skew in full year expectations towards the latter half of the year suggests that management is unlikely to raise its prior FY ’19 guidance at this juncture. As for the risk of a downward revision, the primary concerns remain the status of any existing arrangements with the USPS, the company’s ability to pass along price increases to negotiated service agreement holders, and currency fluctuations.
We note that Pitney Bowes cited a delay in renewing an existing negotiated service agreement with the USPS as a driver of its soft start to the year. We doubt this has much bearing on Stamps.com, however, as commentary following last quarter’s bombshell suggested other existing agreements with the USPS may not be up for renewal this year. We also surmise that management likely took a conservative posture if any agreements were up for discussion considering the outcome of its last negotiation. The 3% surcharge on those with negotiated service agreements may pose more of a risk given the potential for churn, but as mentioned earlier, there does not appear to be any fall-out as of yet. With all this in mind, we expect management to reaffirm its prior guidance for FY ’19.
Although upside Q1 results would certainly be welcome, we expect investors to focus primarily on any potential risks to the company’s remaining USPS-related revenues, whether direct or indirect, and discussions with other major carriers that could bring new economic arrangements to the company. Management’s stance last quarter with respect to the USPS was that not much else is likely to change in the near-term, and we think management will again look to convey a sense of stability with respect to its remaining USPS-related revenues. As for revenue share opportunities with new partners, we anticipate constructive commentary on the potential for new arrangements as Amazon (AMZN) attempts to disrupt the status quo. However, we continue to believe any material developments will require more time to materialize. As we have previously reported, ShipStation appears to be the first multi-carrier solution to be integrated with Amazon’s Shipping Service. While this may simply be a technical integration, we also see it as a promising sign that an economic relationship could be had. We hope management shares more in this regard during the upcoming earnings call. Aside from Amazon, we note that both FedEx and UPS are also focused on fueling growth through penetration into the small and medium-sized business segment through a combination of rate actions, fulfillment offerings, and technology. In its Q1 earnings call, UPS highlighted its integration with Shopify (SHOP), which has brought over 100,000 new customers to the company. We continue to believe the large domestic carriers may look to partner more closely with Stamps.com given the company’s exposure to high-volume shippers.
On the whole, we expect a strong start to the year relative to admittedly diminished expectations. That said, we believe investors will need to remain patient for a more significant catalyst (i.e. new carrier relationships) to emerge. While the cloud of uncertainty around the company is unlikely to lift following the upcoming earnings release, we continue to believe long-term investors are best served by building or adding to positions with the stock trading at just 10.1x and 8.6x our FY ’19 and FY ‘20 adjusted EBITDA estimates, respectively. Our price target remains $150.00, representing a FY ’20 EV/EBITDA multiple of 15x.
Our published model is available here.
Disclosure(s):
The analyst, a member of the analyst’s household, and/or an account in which the analyst exercises discretion hold(s) a long position in the common stock of Stamps.com (STMP).